2003 Honda Accord
Insurance offer$2,000
Settled for$4,000
The check may have been issued. The value may still be worth challenging.
Your insurer determined what it believes your vehicle was worth. That doesn't necessarily mean the valuation was right—or that receiving payment ended your options.
Depending on your policy, claim status, and applicable deadlines, you may still have the Right to Appraisal and an opportunity to challenge the amount of loss.
Years of experienceAuto damage appraisal
Total loss valuationsExperience behind the analysis
Initial file reviewUnderstand your next step
The right comparison can change the conversation. We look at your vehicle’s details, the market evidence, and the adjustments used to arrive at its pre-loss actual cash value.
Let’s take a closer lookWe examine the vehicles used in the insurer’s report and research relevant market comparables. Model, trim, location, mileage, and listing details all deserve a closer look.
These are results from recent successful appraisal settlements. They show how an independent review can change the outcome — not what any particular claim will receive.
Every vehicle and claim is different. Your offer, policy language, and the evidence behind the value determine what’s possible.
Let’s review your offerStart with a free review.
Understand the evidence before deciding.
Typical results from completed appraisal settlements. Past outcomes do not guarantee future results. Every claim is evaluated on its own facts and policy language.
From an everyday driver to a luxury vehicle, the review starts with the evidence that supports its value.
Independent appraisal. Individual attention.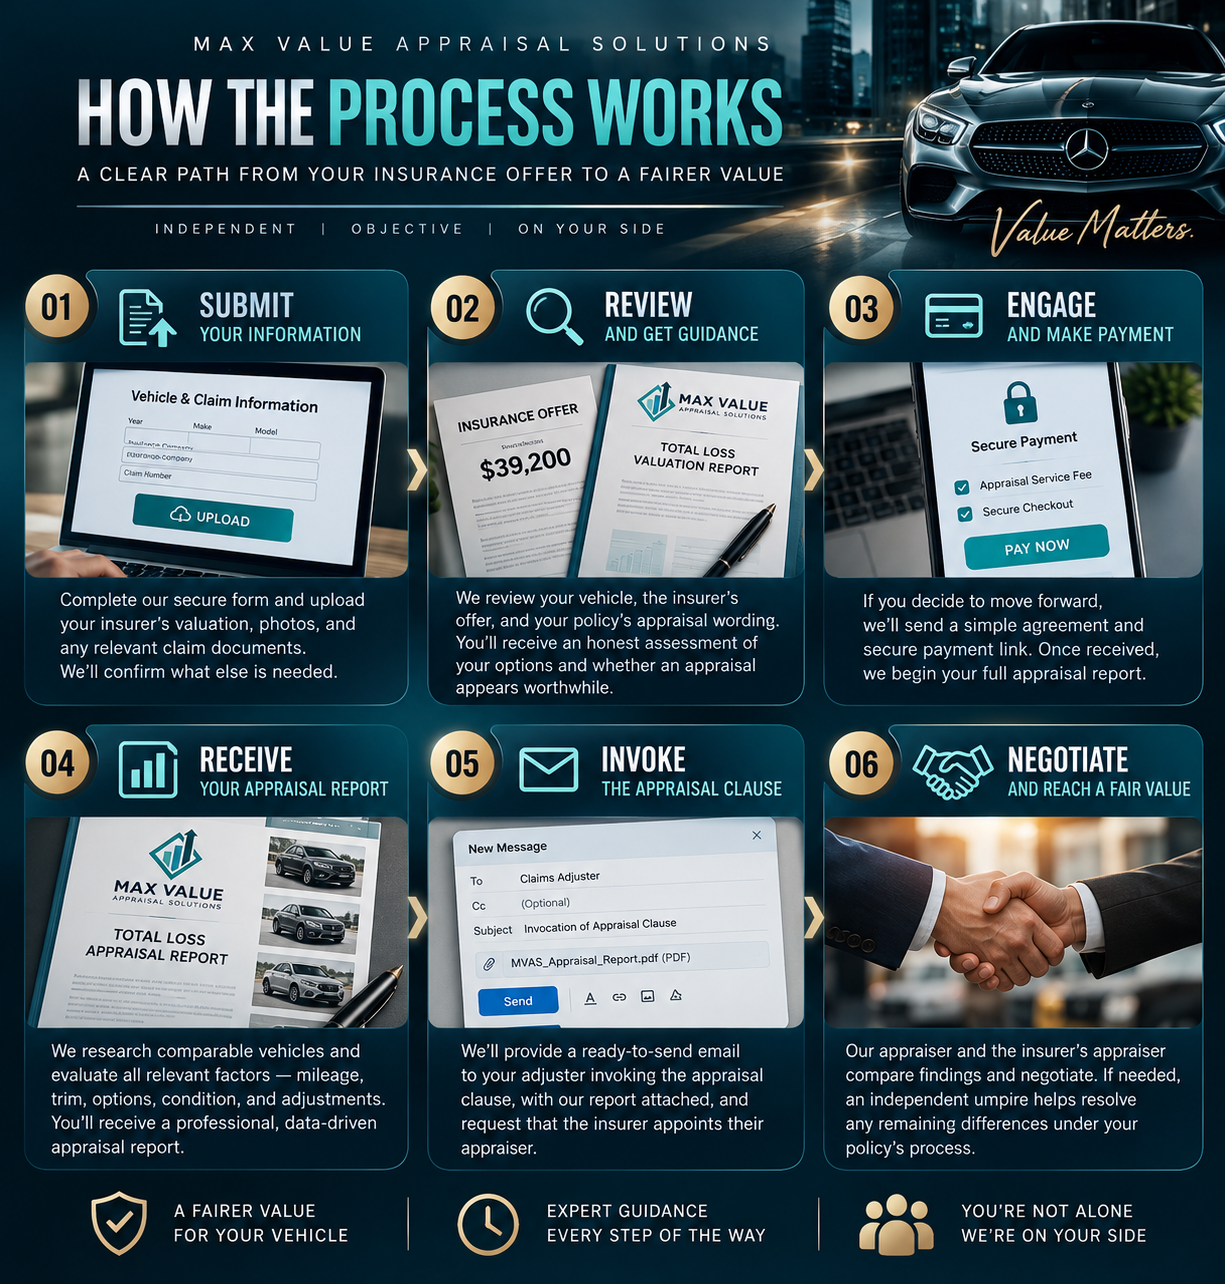
With more than 25 years in auto damage appraisal and 1,000+ total loss valuations, Max Value Appraisal Solutions brings practical experience to a question that matters: what does the evidence support?
Our starting point is simple: an honest review of whether an independent appraisal appears worth pursuing.
Start with an independent review of the value behind it.
A little clarity can make your next step easier. If your question isn’t here, we’re happy to talk it through.
Ask Max Value Start a free reviewIf you disagree with your insurance company about the value of your totaled vehicle, your policy may contain an appraisal provision that allows the value dispute to be handled by independent appraisers. Max Value Appraisal Solutions focuses specifically on total-loss Actual Cash Value disputes.
No. Max Value Appraisal Solutions currently focuses exclusively on total-loss ACV / Right-to-Appraisal claims. We are not accepting diminished-value or repair-clause assignments.
Start with our free review. We look at your insurance valuation, vehicle information, policy situation, and the circumstances of your claim to determine whether an appraisal may make sense.
Not necessarily. Receiving or even accepting an initial payment does not automatically answer whether appraisal rights still exist. Your policy language and claim circumstances matter, so we recommend having the file reviewed before making assumptions.
We independently evaluate your vehicle’s Actual Cash Value using relevant market vehicles, mileage, trim, equipment, condition, and other valuation factors. When appropriate, we prepare the appraisal and participate in the appraisal process with the insurance company’s selected appraiser.
The appraisal provision may allow the two appraisers to select an independent umpire. The umpire reviews the valuation dispute, and an agreement by any two of the three can determine the amount of loss, subject to the wording of the policy and applicable law.
Your free initial review costs nothing. If you decide to hire Max Value Appraisal Solutions, we explain our appraisal fee before you proceed. Under many appraisal provisions, each side pays its own appraiser and shares the cost of an umpire if one becomes necessary.
No. Every vehicle and claim is different. We do not guarantee a specific increase or settlement. Our job is to provide an independent, supportable opinion of your vehicle’s Actual Cash Value.
Your insurance company’s total-loss valuation report is the best place to start. Your policy or appraisal-clause language, vehicle information, mileage, options, condition information, and recent maintenance or upgrade records may also be helpful.
Timing varies depending on the insurance carrier, availability of the other appraiser, whether the appraisers agree, and whether an umpire is needed. After reviewing your file, we can explain what to expect in your particular case.
Possibly. Appraisal rights depend on your insurance policy and the laws that apply to the claim. Submit the file for review and tell us where your policy was issued.
Complete the Free Total-Loss Review form below or call 346-247-8408. We’ll review the basic information and let you know what documents we need next.